Exclusive 20% Discount: LLMs for Quant Research – Build Text Signals & Research Agents You Can Trust (Code: HUI20)
Special 20% Discount for the IBridgePy Community
Save 20% using promo coupon code HUI20 or register directly through our partner link below.
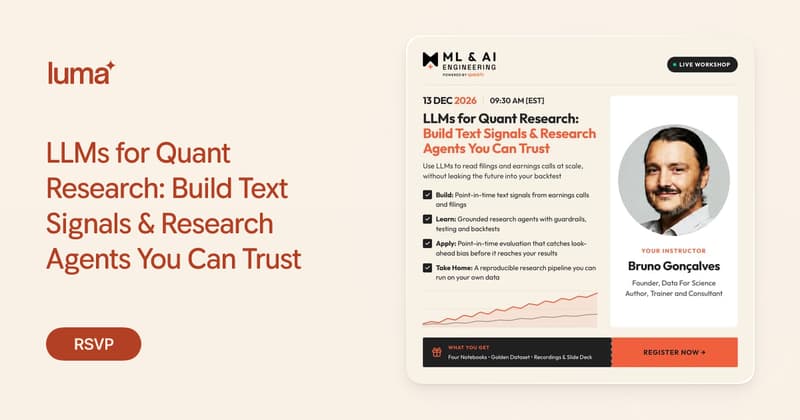
Can large language models generate genuine quantitative trading alpha? The short answer is yes — but only if you know how to extract verifiable sentiment signals, eliminate lookahead bias, and validate evidence through rigorous backtesting.
In this 4-hour live quantitative masterclass hosted by Packt, leading AI and data science educator Dr. Bruno Gonçalves guides you through building practical financial research pipelines. You will convert messy earnings calls and SEC 10-K/10-Q filings into actionable trading signals, build source-backed RAG applications, and deploy financial research agents with strict spending limits and auditability.
As part of our partnership with Packt, the IBridgePy community gets an exclusive 20% discount with coupon code HUI20.
📅 Workshop Snapshot
Sunday, December 13, 2026
9:30 AM – 1:30 PM EST (2:30 – 6:30 PM UTC)
4 Hours • 4 Working Notebooks • Live Q&A
Dr. Bruno Gonçalves (Founder, Data For Science)
Packt - ML & AI Engineering
20% Off with Code HUI20 ($159.99 vs $199.99)
Exclusive Ticket Pricing Breakdown (Coupon: HUI20)
Turn Unstructured Financial Text into Quantitative Signals
Includes 4 working Python notebooks, ~200 labelled examples, and walk-forward validation code. Save 20% today.
Enroll with 20% Discount (Code: HUI20) →Includes live masterclass, 4 production notebooks, evaluation checklists, and full HD recording.
From Text Alpha Signals to Live Trades with IBridgePy
Extracting sentiment scores and earnings guidance revisions from SEC filings is only half the battle. To profit from quantitative research, you must translate text signals into systematic live order execution.
This is where IBridgePy comes in:
- Automated Signal Execution: Ingest the signal outputs generated by your LLM pipeline directly into IBridgePy trading scripts to place orders on Interactive Brokers, TD Ameritrade, or Robinhood.
- Prevent Lookahead Bias: The workshop emphasizes timestamp alignment and point-in-time filing dates. When backtesting in IBridgePy, matching precise release timestamps ensures your simulation reflects genuine market reality.
- Multi-Strategy Allocation: Combine traditional price-action factors with LLM sentiment signals in an ensemble portfolio, rebalancing positions automatically through IBridgePy.
What You Will Learn and Master
- Financial Text Signals: Extract sentiment, guidance changes, and risk disclosures from transcripts and SEC filings, benchmarking against established financial models (e.g. FinBERT).
- Financial RAG Pipelines: Build an SEC filing research system that retrieves relevant snippets, parses complex financial tables, and provides source-cited answers.
- Quant Research Agents: Connect LLMs to live market data and Python quantitative tools with hard spending budgets and human review checkpoints.
- Walk-Forward Backtesting: Validate whether text signals add genuine alpha beyond existing price/momentum factors without data leakage.
- Reproducibility & Governance: Implement audit checklists covering timestamp verification, incremental information tests, and evidence quality.
Meet Your Instructor: Dr. Bruno Gonçalves
Dr. Bruno Gonçalves is the founder of Data For Science, an author, and an international consultant in Machine Learning and Generative AI. With a PhD in Physics of Complex Systems, he was a Data Science Fellow at NYU's Center for Data Science and has trained thousands of data scientists and finance professionals worldwide through O'Reilly, Pearson, and top financial institutions.
Frequently Asked Questions
Click any enrollment button on this page. Promo code HUI20 is applied automatically. You can also enter HUI20 at checkout on Luma to claim your discount.
Attendees receive 4 complete Jupyter notebooks, ~200 labelled financial text evaluation examples, pre-deployment checklists, slides, and full lifetime access to the recording.
Working proficiency in Python and basic data analysis. Familiarity with financial markets or backtesting is helpful but not strictly required.
Elevate Your Quantitative Research with LLMs
Bridge unstructured financial text with systematic trading. Use promo code HUI20 to claim your 20% discount before registration closes.
Register on Luma with 20% Off →Coupon HUI20 applied automatically • 4 Working Notebooks • Access to Recordings