Exclusive 40% Discount: Build and Stress-Test a Multi-Asset Portfolio with Python
Special 40% Discount for the IBridgePy Community
Save 40% using promo code HUI40 or enroll directly through our partner link below.
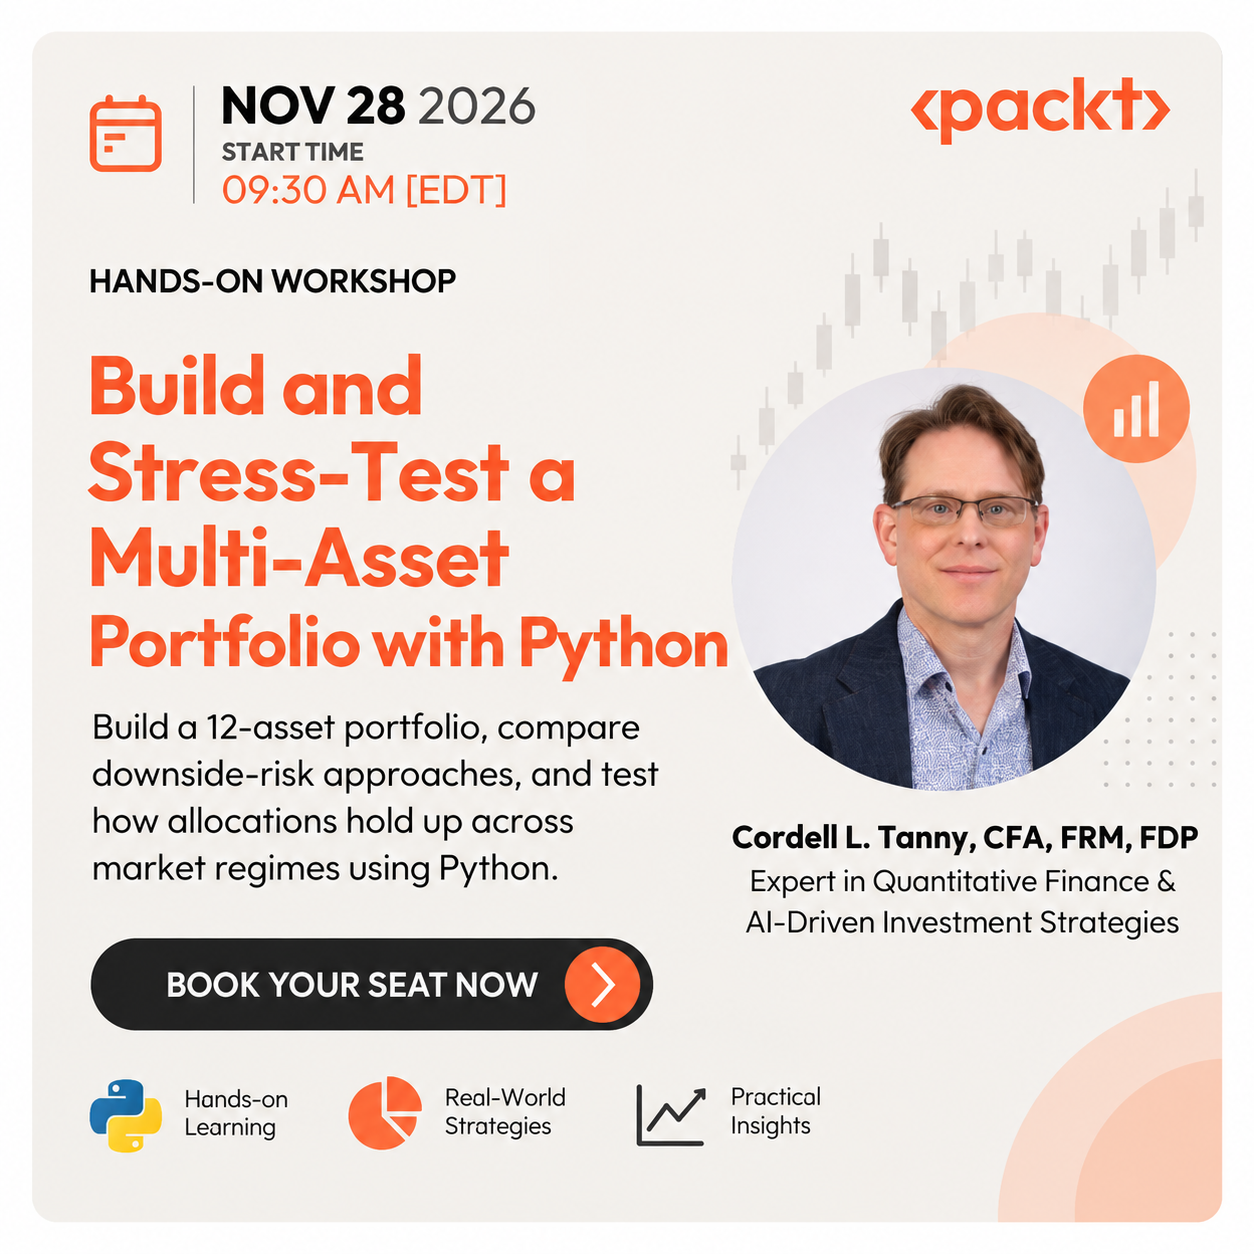
Constructing multi-asset portfolios in volatile, shifting markets requires going far beyond textbook mean-variance optimization. When asset correlations spike during financial crises, standard diversification assumptions can break down overnight.
In this practical, 4-hour live workshop hosted by Packt, quantitative portfolio expert Cordell Tanny, CFA, FRM, FDP guides you through institutional-grade portfolio construction and stress-testing in Python using a real 12-asset universe across global equities, government bonds, credit, inflation protection, real assets, and cash.
We are excited to share that IBridgePy has partnered with Packt to offer our community an exclusive 40% discount with coupon code HUI40.
📅 Workshop Snapshot
Saturday, November 28, 2026
9:30 AM – 1:30 PM EST (2:30 – 6:30 PM UTC)
4 Hours • Live Hands-On Online Workshop
Cordell Tanny, CFA, FRM, FDP
Packt - ML & AI Engineering
40% Off with Code HUI40 ($99.59 vs $165.99)
Ready to Master Multi-Asset Portfolio Stress-Testing?
Seats are limited. The 40% discount is applied automatically when you use our partner registration link.
Enroll with 40% Discount (Code: HUI40) →Includes live workshop access, complete 12-asset case study, reusable Jupyter notebooks, and certificate of completion.
How This Connects with IBridgePy Algorithmic Trading
A major challenge quant practitioners face is the gap between backtesting/portfolio modeling and live execution. You can model optimal weights in a notebook, but how do you systematically trade and rebalance that portfolio in live brokerage accounts?
This is where IBridgePy comes in:
- Automated Multi-Asset Execution: Feed optimal portfolio weights calculated from Cordell's CVaR and downside-target models directly into IBridgePy execution scripts connecting to Interactive Brokers, TD Ameritrade / Charles Schwab, or Robinhood.
- Scheduled Rebalancing & Drift Control: Use IBridgePy's scheduler to monitor asset class weight drifts weekly or monthly, generating rebalancing re-orders automatically without manual intervention.
- Programmatic Risk Bounds: Implement hard drawdown stops, max position sizing, and leverage guards inside your IBridgePy trading algorithms, aligning your live execution with the stress-test results obtained in this workshop.
- Seamless Python Ecosystem: Because IBridgePy runs in standard Python environments, the portfolio optimization code and notebooks from this session can be directly imported and orchestrated by your trading bots.
What You Will Build and Master:
- 12-Asset Universe Deep Dive: Analyze return, volatility, skewness, kurtosis, correlation, and regime-dependent diversification across global equities, government bonds, corporate credit, inflation protection, real assets, and cash.
- Parametric Simulation & Block Bootstrapping: Generate robust forward inputs instead of naively relying on a single historical return matrix.
- Downside Risk Analytics: Measure drawdowns, recovery durations, sequence-of-returns risk, Sortino, Calmar, and Omega ratios.
- Advanced Frontier Optimization: Construct efficient frontiers and contrast traditional mean-variance portfolios with CVaR and downside-target allocations.
- Regime Analysis & Illiquid Asset Pricing: Understand how asset correlations shift during market stress and how stale pricing artificially depresses observed volatility.
- AI-Assisted Risk Memo: Use an LLM to translate quantitative stress-test tables into an institutional-grade investment risk memo.
Meet Your Instructor: Cordell Tanny, CFA, FRM, FDP
Cordell Tanny is Managing Director at Trendlogic Financial Software and a seasoned quantitative portfolio construction specialist. With decades of institutional asset allocation experience, Cordell holds the prestigious CFA (Chartered Financial Analyst), FRM (Financial Risk Manager), and FDP (Financial Data Professional) designations.
Cordell specializes in turning cutting-edge quantitative finance research into practical, production-ready Python workflows that portfolio managers, quants, and serious private investors can execute immediately.
Every Registered Attendee Receives:
- Complete 12-Asset Case Study Dataset: Real-world market data covering multiple economic cycles.
- Full Reusable Python Notebooks: Clean, well-documented Jupyter notebooks implementing all models and optimizations.
- Factor Model Reference Notebook: Ready-to-adapt templates for equity and asset-class factor analysis.
- Full Session Recording & Slide Deck: Unlimited post-event access to revisit every derivation and line of code.
- Certificate of Completion: Official credential issued by Packt recognizing your advanced portfolio analysis training.
Frequently Asked Questions
Click any enrollment button on this page. Coupon code HUI40 is automatically passed in the Luma checkout URL. You will see the price drop from $165.99 to $99.59.
No problem! All registered ticket holders receive full HD recordings of the entire workshop along with all code repositories and notebooks.
Basic familiarity with Python and tabular data (pandas/numpy), plus fundamental investment concepts (returns, volatility, Sharpe ratio). You do not need prior machine learning or advanced optimization experience.
Claim Your 40% Community Discount
Upgrade your quantitative asset allocation process and build stress-test models that stand up to real market chaos. Use code HUI40 to reserve your ticket now.
Register on Luma with 40% Off →Discount applied automatically • 100% Online • Access to Notebooks & Recordings Included